Industries: insurance brokers
Insurance broker CRM built around renewals, claims and the Consumer Duty
2023
Your broking system holds the policies, premiums and insurer links. We build what it leaves to the team: demands and needs recorded at the client's table, a renewals list that flags what needs a person, claims a client can follow and an inbox sorted before 9am.
A broking firm runs on renewals, claims and trust
An insurance broker CRM rarely has to replace anything. Most UK brokers already run a broking system that holds the policies, the premiums, the commission and the trading links with insurers, and it should stay. What it seldom fixes is the rest of the day: claims arriving in three inboxes, renewals checked on a spreadsheet, demands and needs on paper, and clients ringing to ask where their claim stands.
We build what sits beside your broking system, sized for a sole trader, a team of ten or a firm of forty, and we connect where your system allows it. Below you will find what that looks like need by need, what each size of firm needs, and the FCA rules it has to respect.
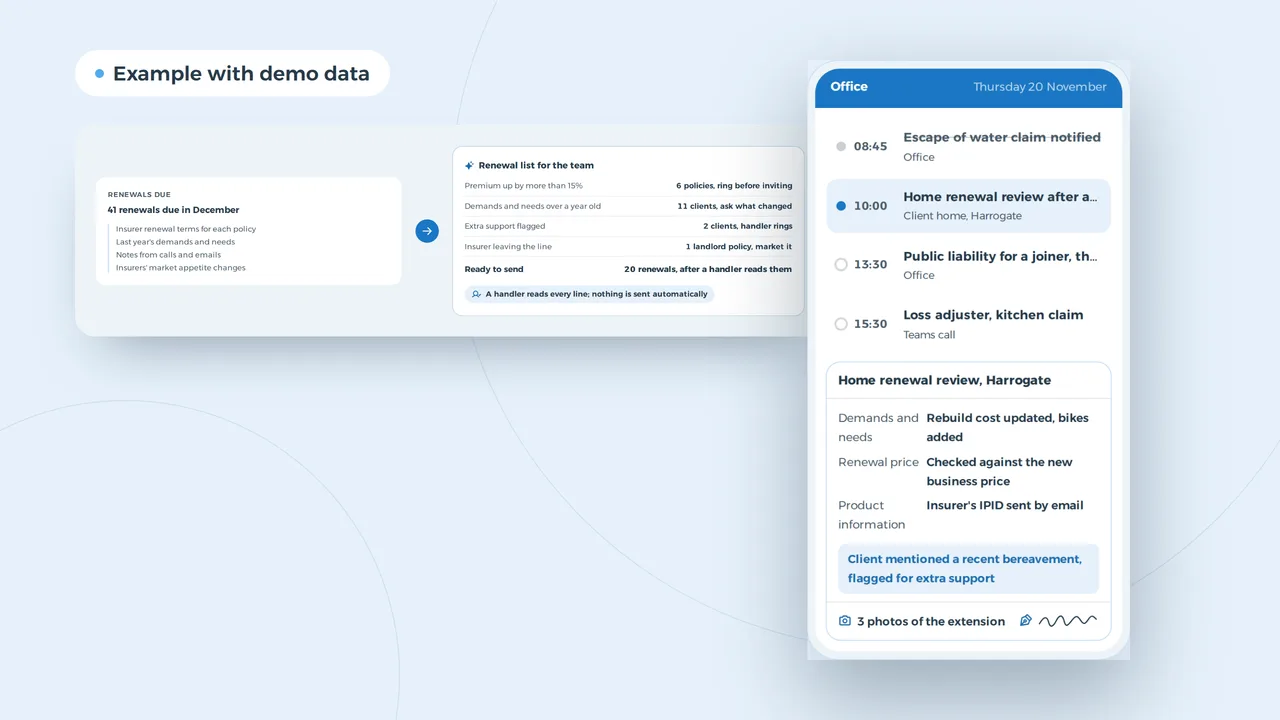
A broker's day on the phone, with the renewal review open
- Demands and needs are on fileWhat the client asked for, what you recommended and why: stored with the client record, ready when a claim comes in.
- This morning's claim keeps movingThe notification went to the insurer. The app shows what the adjuster still needs and when the visit is booked.
- Client data stays in the office systemThe phone shows the appointment and the record. Photos and documents go straight to the file, not the camera roll.
An example of what we can build, with made-up names and appointments. You choose what the record shows.
Where a broker's week leaks time
Brokers earn their living from advice and from claims that end well. The time goes on the work around them. This is an ordinary Thursday in an office of four handlers.
| When | What happens | Where it pinches |
|---|---|---|
| 8.30am | Claims after a stormy night, by email, phone and WhatsApp | Notifications in three channels, and the same client rings twice |
| 10am | A renewal review at a client's home | Notes on paper, typed up in the evening; demands and needs never reach the record |
| 1.30pm | Marketing a risk to three insurers | Every insurer portal has its own form, and the comparison lives in a spreadsheet |
| 3pm | Renewal invitations for next month | Price changes, lapsed direct debits and cancellations on a list nobody owns |
| 4.30pm | Chasing claims with adjusters and repairers | The client does not know what is still missing and rings again |
| All week | Training hours, complaints, Consumer Duty data | Hours per person in a separate file, outcomes data pulled together by hand before the board meets |
None of it is big. Together it takes hours a week that do not go to clients. The risk sits in what gets missed: a renewal sent without a price check, or a demands and needs statement you cannot find when a claim is disputed.
Demands and needs recorded at the kitchen table
ICOBS asks you to specify a client's demands and needs before the contract is concluded, and to explain your recommendation when you advise. In many firms that still happens on a paper form scanned later, or in a Word file on a shared drive. It holds up until a claim is declined and someone asks what the client told you at the start.
On a phone or tablet, the handler fills in demands and needs at the client's kitchen table. The form lands in the record with the date, the e-signature and the product information you sent. Your colleagues see it, and your broking system gets the policy as usual. That is the core of an insurance broker CRM built to your process: follow-up, quotes and client history, without duplicating the policy administration. The guide to CRM costs sets out what drives the price.
December's renewals, sorted before the invitations go out
An example of what we can build, with made-up renewals and figures. The AI sorts, a person decides. Client data stays inside the firm's own environment.
Renewals checked before the invitation goes out
Renewals are where the Consumer Duty gets tested most. For home and motor, ICOBS 6B says the renewal price may not be higher than the equivalent new business price, and that binds brokers who add their own fee or commission too. Beyond price, a renewal is the moment to ask whether the cover still fits.
A renewals list that reads each insurer's terms against the client file sorts the month for you: the policies where the premium jumped, the clients whose demands and needs are more than a year old, the ones flagged for extra support, and the line an insurer has left. A handler reads every line before anything goes out. The same approach works for the shared inbox, where AI sorts incoming messages and drafts replies for a person to send. A private AI assistant on your own documents keeps client data inside your own environment.
An escape of water claim in five stages, with the estimate set against the interim payment
The client sees the stages and what is still missing through a secure link. Emails with the adjuster and the insurer stay in the file.
An example of what we can build, with a made-up client and amounts.
A claims file the client can follow
After a storm, dozens of claims arrive at once. Every client wants the same answers: has my claim gone in, when is the adjuster coming, what do you still need from me. Each of those calls is five minutes the claims handler does not spend on the claim itself.
In a client portal, the client sees the stages of the claim, uploads photos and repair quotes, and knows which document is still missing. Emails with the adjuster and the insurer stay in the claims file, not in the inbox of whoever covered that week. Where your broking system exposes data, we connect to it so nobody keys a claim in twice.
Found as a broker in your own town
A family buying a house or a landlord with a new flat types 'insurance broker' and their town. The three firms on the map get the call. A Google Business Profile with hours and photos, reviews from clients and local SEO decide which three those are.
Then the website has to carry it: a page for homeowners, one for landlords, one for trades and small firms, your FCA status and complaints procedure, and a quote form that asks what the insurers will ask. We cover that in detail in insurance broker website design.
A search in Harrogate that turns into a quote request
Quote request
Landlord cover for two flats, renewal on 1 January
Priya, Knaresborough, yesterday 21:10
- A page per client type: homeowner, landlord, trade, small firm
- A Google profile with hours, office photos and reviews
- A quote form that asks what the insurers will ask
Example with made-up brokers and reviews.
Insurance broker CRM by size of firm
A sole trader broker needs no ERP and usually no custom platform. A firm of forty across three offices needs more than a broking system and a shared inbox. This is what we would build at each size.
| Firm | What usually does the job | What we would add |
|---|---|---|
| Sole trader | Your broking system and a good website | A site with a quote form per client type, a Google profile and digital demands and needs |
| A team of five | A shared list of tasks and renewals | A CRM for follow-up and quotes, a claims inbox that sorts itself, a link to your broking system |
| A firm of 20 to 50 | Separate people for claims, new business and accounts | A client portal and a dashboard with open claims, renewals, complaints and training hours per person |
| Larger, or several offices | A platform of your own beside the broking system | Roles per office, an audit log and board reporting for the Consumer Duty, as in bespoke software development |
When the team grows you hire people with CII exams, and they apply on their phones. If your firm still runs on spreadsheets, start with replacing Excel with software. The guide to custom software costs explains what bespoke work costs. Engineering firms and payroll bureaus also run on case files, deadlines and a regulator; what we build there is close to what a broker needs.
An account handler vacancy that people apply for on their phones
An example with made-up names; you choose what the form asks, from claims experience to CII exams.
FCA rules your systems have to hold
These are the rules that most often have to live inside a broker's systems, checked against the FCA Handbook and the FCA's own pages on 31 October 2026.
| Rule | What it asks | What the software does |
|---|---|---|
| FCA authorisation | Arranging insurance is a regulated activity. Your firm is authorised by the FCA, or is an appointed representative of a firm that is, and appears on the Financial Services Register | Holds your firm reference number and each person's role in one place |
| Consumer Duty | Since 31 July 2023 for open products and 31 July 2024 for closed ones, firms must deliver good outcomes for retail customers, and the board reviews this at least once a year | Records outcomes per client: support needs, complaints, renewals and claims, ready for the annual board report |
| Demands and needs (ICOBS 5.2) | Before the contract is concluded, you specify the client's demands and needs, and the policy must be consistent with them; when you advise, you explain why | The demands and needs form in the client record, with the date and what was recommended |
| Renewal pricing (ICOBS 6B) | Since 1 January 2022, a home or motor renewal price may not be higher than the equivalent new business price | The renewals list shows the renewal price beside the new business price and flags a gap before the invitation goes out |
| Communications (ICOBS 2.2) | Everything you send clients, including promotions, is clear, fair and not misleading | Website pages and email templates checked once, then reused |
| Training | At least 15 hours of professional training a year for staff involved in insurance distribution | Hours and certificates per person, with a reminder when someone falls behind |
| Complaints (DISP 1.6) | A final response within eight weeks; the client then has six months to go to the Financial Ombudsman Service | A complaints log with the eight-week date counted from receipt |
| UK GDPR | Claims and protection cover involve health data, a special category | Access by role, an audit log and data held in the UK or EU; see UK GDPR vs EU GDPR |
Your compliance lead or network decides how you meet each rule. The software makes it easy to show what you did.
A firm with 3,000 policies, in hours
| Task | Now, per month | With a renewals list, portal and dashboard |
|---|---|---|
| Renewal checks | 33 hours | 13 hours, at 3 minutes each once the list does the comparing |
| Calls about where a claim stands | 29 hours | 14 hours, if half the clients check online |
| Consumer Duty data for the board | 4 hours | 1 hour |
| Total | 66 hours | 28 hours |
In this example, close to 38 hours a month go back to clients and new business. Your own numbers will give a different answer; we work them out together in the first conversation.
A conversation first, then a fixed price per project
- A conversation about your weekWe go through an ordinary week: where claims come in, how renewals are checked, what lives in spreadsheets and what your broking system lets us reach.
- A proposal with a fixed priceWhat we build, in which order, with a fixed price per project. A website starts from 1,500 euro; the rest we price after that first conversation.
- Built beside your broking systemWe build in parts your team uses straight away, and connect to your broking system where it allows it.
- Live with your own teamWe start with a handful of clients and handlers, then move the rest across once it works.
We have no broking firm as a client yet, but the Business Centrum management platform also holds case files, documents and an activity log, encrypted, with two-factor sign-in and a portal where clients follow along.
Brokers often ask us
Does this replace our broking system?
No. Policies, premiums, commission and insurer trading stay in your broking system. We build what sits beside it: follow-up, a claims portal, demands and needs, a renewals list and your website, and we connect where your supplier allows it.
Can you connect to insurer portals?
That depends on what the insurer or your broking system offers. Where there is an integration or an export, we use it. Where there is none, we make it a clear task for the person who opens the portal, rather than scraping data off a screen.
Does a CRM help with the Consumer Duty board report?
It helps you gather the evidence. When renewals, complaints, claims and support needs are recorded per client, the outcomes data for the annual board report comes from the system instead of from a week of spreadsheets. The judgement on whether outcomes are good stays with your firm.
Can AI read our claims emails under UK GDPR?
Yes, with safeguards. You sign a data processing agreement, data stays in the UK or EU, health data gets extra protection, and a person approves every reply. Write down which tasks AI may do before you switch it on.
How long do complaints have before they go to the Ombudsman?
You have eight weeks to send a final response. If none has gone out by then, the client can go to the Financial Ombudsman Service; after a final response, they have six months to do so. A complaints log that counts those dates for you takes the guesswork out.
What does a website for a broker cost?
A website starts from 1,500 euro. The price depends on the number of pages, the quote forms and whether a portal or integration comes with it. After the first conversation you get a fixed price.
Custom software
How VBS helps you with this
We build the platform your business runs on every day: your spreadsheets, emails and paperwork in one system that does what you do.
- Your workflow mapped first, then a fixed price
- Screens for the office, the client and the road
- Hosting, backups and security managed by us on AWS
How we approach it is on our page about Custom software.
Fewer calls about claims, more time for clients?
Tell us how renewals, claims and the inbox run in your firm today. We will say what we would build beside your broking system, with a fixed price per project.
Rather get in touch right away?